

' fill='%23fff'%3E%3Cpath d='M16 7a3.5 3.5 0 1 1 0-7 3.5 3.5 0 0 1 0 7z'/%3E%3Cpath d='M27 7.05l-.028.008-.026.008a7.112 7.112 0 0 0-.188.055c-1.163.341-6.808 1.933-10.785 1.933-3.696 0-8.83-1.375-10.472-1.842A4.61 4.61 0 0 0 5 7.05c-1.188-.313-2 .893-2 1.996 0 1.092.98 1.612 1.972 1.985v.017l5.95 1.86c.609.232.771.47.85.677.259.662.053 1.972-.02 2.43l-.363 2.812L9.378 29.84l-.017.092-.014.08c-.145 1.009.596 1.988 2 1.988 1.225 0 1.766-.846 2-1.996.234-1.15 1.75-9.848 2.625-9.848s2.677 9.848 2.677 9.848c.235 1.15.775 1.996 2 1.996 1.408 0 2.15-.984 2-1.996a3.591 3.591 0 0 0-.047-.254l-2.04-10.92-.361-2.813c-.262-1.638-.052-2.18.02-2.306a.07.07 0 0 0 .005-.01c.067-.125.375-.405 1.092-.674l5.58-1.95c.034-.01.068-.02.101-.033 1-.375 2-.894 2-1.996 0-1.102-.811-2.31-1.999-1.998z'/%3E%3C/g%3E%3Cdefs%3E%3CclipPath id='clip0_1_1506'%3E%3Cpath fill='%23fff' d='M0 0h32v32H0z'/%3E%3C/clipPath%3E%3C/defs%3E%3C/svg%3E)

Highlights:
- Understanding Your CIBIL Report
- How to Download your CIBIL Report Online?
- How to Use Your CIBIL Report to Improve Your Score?
- What Can You Find in a CIBIL Report?
- Why Reviewing Your CIBIL Report Matters?
- Tips to Maintain a Good CIBIL Score
- Difference Between CIBIL Score and CIBIL Report
Your credit report is reflects your financial management. If you are planning to apply for a Home Loam, or simply maintain a healthy credit record, your CIBIL report plays a central role in determining how lenders assess your creditworthiness.
The process of checking your CIBIL score and downloading your CIBIL report online is simple. Let’s explore how you can do it, what your report includes, and why it matters for your financial journey.
What is a CIBIL Report?
A CIBIL report—compiled by TransUnion CIBIL—is a detailed record of your credit history. It contains every loan, credit card, and repayment activity associated with your name and PAN number.
Lenders review this report when you apply for credit, using it to gauge your reliability as a borrower. The accompanying CIBIL score, a number between 300 and 900, sums up your credit behaviour. A higher score (usually above 750) reflects responsible borrowing and timely repayment.
How to Download your CIBIL Report Online?
Here’s how you can check your score online:
- Access the CIBIL form.
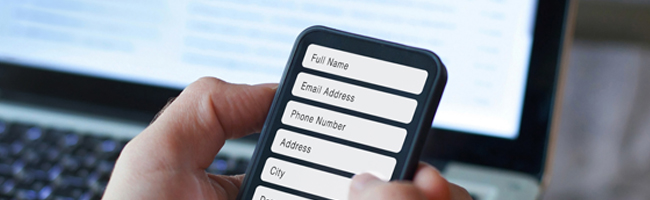
- Fill in your full name, mobile number, and date of birth.
- Enter PIN code, PAN, and email address.
- Generate OTP and confirm your identity through a one-time password sent to your mobile.
- Your score appears on the screen.
- Once you’ve viewed your score, it’s good practice to download your CIBIL report online for reference. You can click on ‘Download Report’ to access a free credit report, which is available once a year at no cost.
How to Use Your CIBIL Report to Improve Your Score?
Your CIBIL report helps you understand what’s helping or hurting your credit score. Here’s how you can use it effectively:
- Check personal and account details – Ensure your name, PAN, and loan details are accurate (errors can impact your score)
- Review repayment history – Identify missed or delayed payments and focus on maintaining timely repayments going forward
- Monitor credit utilisation – Keep your usage below 30 - 40% of your credit limit to show financial discipline
- Limit credit enquiries – Too many loan or card applications can lower your score
- Review DPD (Days Past Due) – This highlights past delays and helps you avoid repeating them
What Can You Find in a CIBIL Report?
When you open your report (whether online or as a downloaded PDF), you’ll see that it’s neatly divided into several key sections. Each reflects your financial habits and helps lenders assess your creditworthiness.
Here’s a detailed breakdown of what you’ll find inside your CIBIL report:
1. Personal Information
This section contains your name, gender, date of birth, and PAN Card details. These identifiers ensure your report is uniquely linked to you and not mixed with anyone else’s records.
2. Contact Details
Lists your current and previous residential addresses, phone numbers, and email IDs—helping lenders cross-check your correspondence information.
3. Employment Information
Shows your occupation and income range as reported by lenders when you first applied for credit.
4. Account Information
Perhaps the most important section, this includes:
- All your current and closed loans and credit cards.
- Account numbers, opening dates, and sanctioned amounts.
- Outstanding balances and repayment timelines.
- Monthly repayment patterns (up to 36 months).
If you have ever missed an EMI or paid late, this is where it shows.
5. Payment History
A month-by-month record of your repayments—indicating whether dues were cleared on time. Consistent “000” or “STD” entries (meaning standard payment) indicate good credit management.
6. Enquiry Information
This lists all the times lenders have checked your credit file when you applied for new credit. Too many recent enquiries can temporarily affect your score.
7. CIBIL Score Summary
Finally, this is where your score—ranging from 300 to 900—is displayed, along with an overview of your credit profile’s strength.
Together, these sections form a comprehensive picture of your credit history and financial reliability.
Why Reviewing Your CIBIL Report Matters?
Regularly reviewing your CIBIL report helps you:
- Catch Errors Early: Occasionally, incorrect entries or duplicate loans may appear. Identifying them early prevents complications during loan applications.
- Spot Unauthorised Activity: Regular reviews help you detect potential fraud or misuse of your personal details.
- Track Financial Progress: As you clear dues or close old loans, your credit score improves—and your report shows this progress.
Tips to Maintain a Good CIBIL Score
Once you have your report, maintaining your credit health becomes easier with a few consistent habits:
- Pay all EMIs and credit card bills on or before their due dates.
- Keep your credit utilisation below 30% of your limit.
- Avoid applying for multiple loans simultaneously.
- Retain older credit accounts to maintain a longer credit history.
- Check and download your CIBIL report online regularly to stay updated.
Difference Between CIBIL Score and CIBIL Report
While people often use the terms CIBIL score and CIBIL report interchangeably, they are not the same thing. Both are connected—but serve different purposes when it comes to assessing your financial profile.
Here’s how they differ:
| Aspect | CIBIL Score | CIBIL Report |
|---|---|---|
| Definition | A three-digit numeric summary of your credit behaviour | A detailed record of your credit history, including all loans, cards, and repayments |
| Range | Between 300 and 900 | No numerical range—it’s a comprehensive document |
| Purpose | Quickly shows your creditworthiness at a glance | Provides lenders with deeper insights into your credit activity |
| Frequency of Change | Can change monthly based on repayment and credit usage | Updates whenever your financial activity changes |
| What It Includes | The overall score derived from your report data | Details like personal info, account summaries, repayment records, and enquiry history |
| Usage | Used by lenders as a preliminary check for loan eligibility | Used for in-depth credit assessment before loan sanction |
In short, your CIBIL score gives a snapshot of your credit health, while your CIBIL report provides the complete story behind that score.
Your CIBIL report is a snapshot of your current finances. It also determines the roadmap for your financial future. By regularly checking and understanding it, you stay one step ahead in achieving your goals.
DISCLAIMER:
While care is taken to update the information, products, and services included in or available on our website and related platforms/websites, there may be inadvertent errors or delays in updating the information. The material contained in this website and on associated web pages, is for reference and general information purposes, and the details mentioned in the respective product/service document shall prevail in case of any inconsistency. Users should seek professional advice before acting on the basis of the information contained herein. Please take an informed decision with respect to any product or service after going through the relevant product/service document and applicable terms and conditions. Neither Bajaj Housing Finance Limited nor any of its agents/associates/affiliates shall be liable for any act or omission of the Users relying on the information contained on this website and on associated web pages. In case any inconsistencies are observed, please click on contact information.
Frequently Asked Questions
No, checking your own CIBIL score is considered a soft enquiry and does not affect your credit score. A hard enquiry is typically made only when you apply for a loan or credit card, and a lender reviews your credit report.
A CIBIL score is a three-digit number that summarises your creditworthiness based on your credit history. A CIBIL report is a detailed document containing your credit accounts, repayment history, credit enquiries, and other information used to calculate your score.
Your PAN card is an important identifier used to retrieve your credit information. However, you will generally need to provide additional details, such as your name, date of birth, registered mobile number, or identity verification, to access your CIBIL score securely.
Your CIBIL score is updated when lenders submit fresh credit information to the credit bureau. The frequency of updates may vary across lenders, so changes in your repayment behaviour or credit usage may take some time to appear in your credit report.
If you notice incorrect information in your CIBIL report, you can raise a dispute with CIBIL through its official website. The bureau will coordinate with the concerned lender to verify the information and update your report if any inaccuracies are confirmed.
Trending Articles
loan+against+property Loan Against Property
[N][T][T][N][T]
How to Pay MCD Property Tax in Delhi2025-04-21 | 3 min
loan+against+property Loan Against Property
[N][T][T][N][T]
How to Apply for a Mortgage Loan?2025-03-05 | 3 min
loan+against+property Loan Against Property
[N][T][T][N][T]
A Guide to Kaveri Online Services Portal for Property Registration in Karnataka2025-04-01 | 3 min
loan+against+property Loan Against Property
[N][T][T][N][T]
Delhi Property Registration Guide: Understanding Registration, Charges and Circle Rates2025-11-12 | 3 min

loan+against+property Loan Against Property
[N][T][T][N][T]
Understanding SDMC Property Tax: A Guide to Online and Offline Payment Methods2025-05-08 | 3 min
loan+against+property Loan Against Property
[N][T][T][N][T]
Property Mortgage Loan: A Smart Financing Option for Businesses2025-03-10 | 3 min
loan+against+property Loan Against Property
[N][T][T][N][T]
Bhu Bharati Telangana: Your Guide to Seamless Land Record Management2025-07-11 | 3 min
loan+against+property Loan Against Property
[N][T][T][N][T]
A Senior Citizen’s Guide to Reverse Mortgage: Meaning, Benefits and Key Insights2025-04-21 | 3 min
loan+against+property Loan Against Property
[N][T][T][N][T]
Understanding OTC and PDF in Loan Against Property2025-05-05 | 3 min
loan+against+property Loan Against Property
[N][T][T][N][T]
A Guide to Viewing Jharkhand Land Records Online via JharBhoomi Portal2025-04-01 | 3 min
loan+against+property Loan Against Property
[N][T][T][N][T]
Guntha to Acre Conversion – A Simple Guide to Land Measurement2025-06-19 | 3 min
loan+against+property Loan Against Property
[N][T][T][N][T]
Property Registration in Bihar 2025: A Complete Guide to Charges, Process and Documents2025-11-12 | 3 min
loan+against+property Loan Against Property
[N][T][T][N][T]
Stamp Duty and Property Registration Charges in Assam2025-11-12 | 3 min
loan+against+property Loan Against Property
[N][T][T][N][T]
What Are the Eligibility Criteria for Obtaining a Loan Against Property?2023-03-28 | 4 min
loan+against+property Loan Against Property
[N][T][T][N][T]
Understanding the Loan-to-Value (LTV) Ratio: Meaning, Formula and Importance2025-04-01 | 2 min
loan+against+property Loan Against Property
[N][T][T][N][T]
Top Benefits of a Loan Against Property Over Collateral-Free Loans2024-01-09 | 4 min
loan+against+property Loan Against Property
[N][T][T][N][T]
Mortgage Loan Against Vacant Land: A Feasible Way to Unlock Property Value2025-05-05 | 3 min
loan+against+property Loan Against Property
[N][T][T][N][T]
Everything You Wanted to Know About Loan Against Property2023-12-16 | 5 Min
loan+against+property Loan Against Property
[N][T][T][N][T]
Why Loan Against Property Can be a Good Credit Option for a Startup Business?2023-12-22 | 5 Min
loan+against+property Loan Against Property
[N][T][T][N][T]
A Guide to Loan Against Property for Doctors